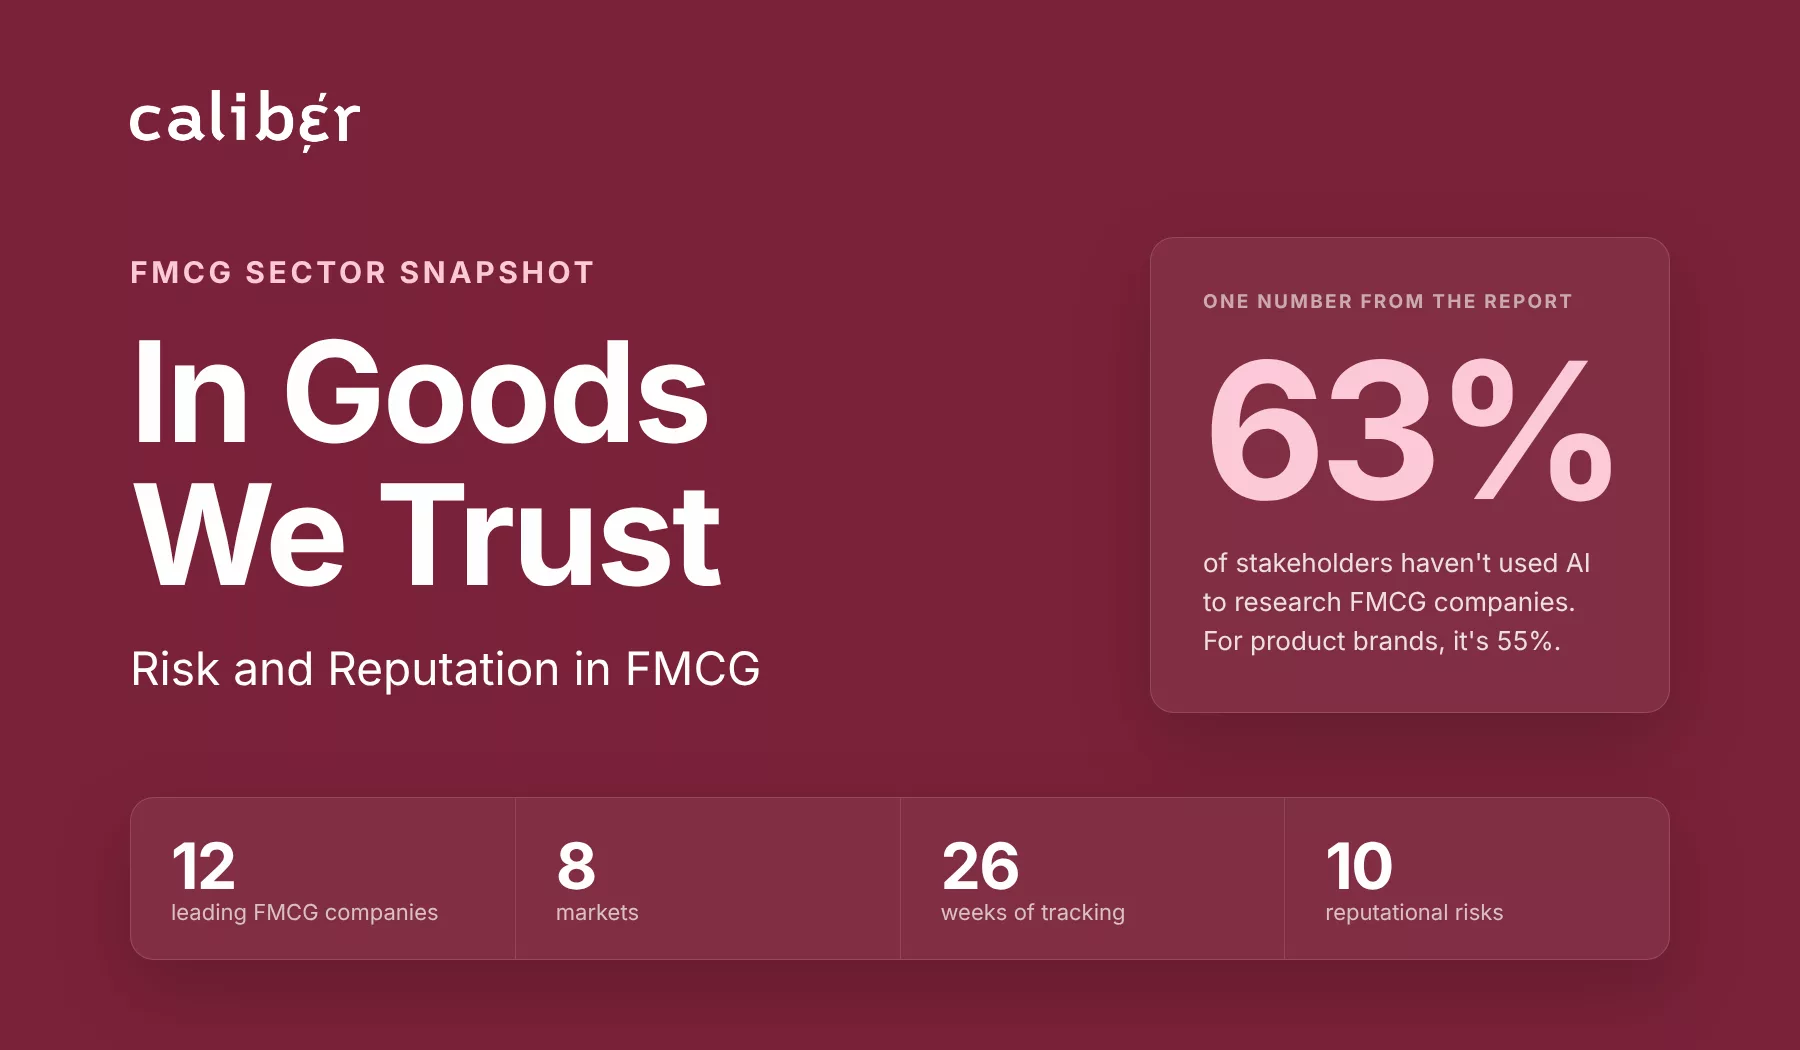
The FMCG industry is one of the most trusted sectors in business, but it has nowhere to hide when something goes wrong. In the first half of 2026, Caliber tracked stakeholder perceptions of 12 of the world’s largest fast moving consumer goods companies across eight markets. The sector beat the local “all sector” average in six of those markets. Its average global Trust & Like Score (TLS) still dropped sharply twice: once in late January, as an infant formula recall spread, and again in early May, amid a cost-of-living squeeze and a $1 billion US lawsuit over ultra-processed foods.
The data comes from Caliber’s report In Goods We Trust: Risk and Reputation in FMCG, a September 2026 sector snapshot. This article covers how the FMCG sector’s reputation moved in 2026, what drives trust in FMCG companies, which brands lift their parent company, and which of 10 reputational risks cost the most trust.
Key takeaways
- The FMCG sector is more trusted than the local average in most markets. According to Caliber’s 2026 FMCG report, the sector outscores the all-sector index in six of eight markets. Germany is the main exception, four points below.
- Trust runs upward, damage doesn’t. People who link more product brands to Nestlé or P&G trust the parent company more. A crisis at one brand stayed with that brand.
- The costliest risks are the ones companies control. People who doubt FMCG companies source responsibly give the sector a TLS of 53, compared with 78 among those who don’t.
- AI users trust FMCG companies more. They give FMCG companies a TLS of 78, compared with 68 among people who don’t use AI tools.
What is the FMCG industry?
The FMCG industry, short for fast moving consumer goods, covers everyday products that sell quickly, at low cost, and in high volume. FMCG products include packaged food and drinks, toiletries, cosmetics, and household cleaning goods. Shoppers buy them often and replace them fast, which is why FMCG brands sit so close to daily life.
That closeness is the sector’s biggest reputational asset and its biggest exposure. Think of a leading brand, and the first one that comes to mind is often an FMCG product: your coffee, your cereal, your shampoo, or your laundry detergent. The same familiarity means stakeholders notice quickly when a product fails, a price rises, or an ingredient comes under suspicion.
FMCG products and the companies behind them
The 12 FMCG companies in Caliber’s study are Associated British Foods, Colgate-Palmolive, Danone, General Mills, Kraft Heinz, Mars, Mondelez International, Nestlé, P&G, PepsiCo, the Coca-Cola Company, and Unilever. Caliber calls them “the Global 12.” Between them, they own many of the world’s best-known food, drink, personal care, and household brands.
Branded houses vs houses of brands
FMCG companies broadly follow one of two models, as Quartr’s analysis of the consumer goods sector describes. In a branded house, such as the Coca-Cola Company, the brand and the company are effectively the same. In a house of brands, such as Nestlé, P&G, or Unilever, each product brand carries its own reputation with consumers, while the parent company answers separately to investors, regulators, and wider society.
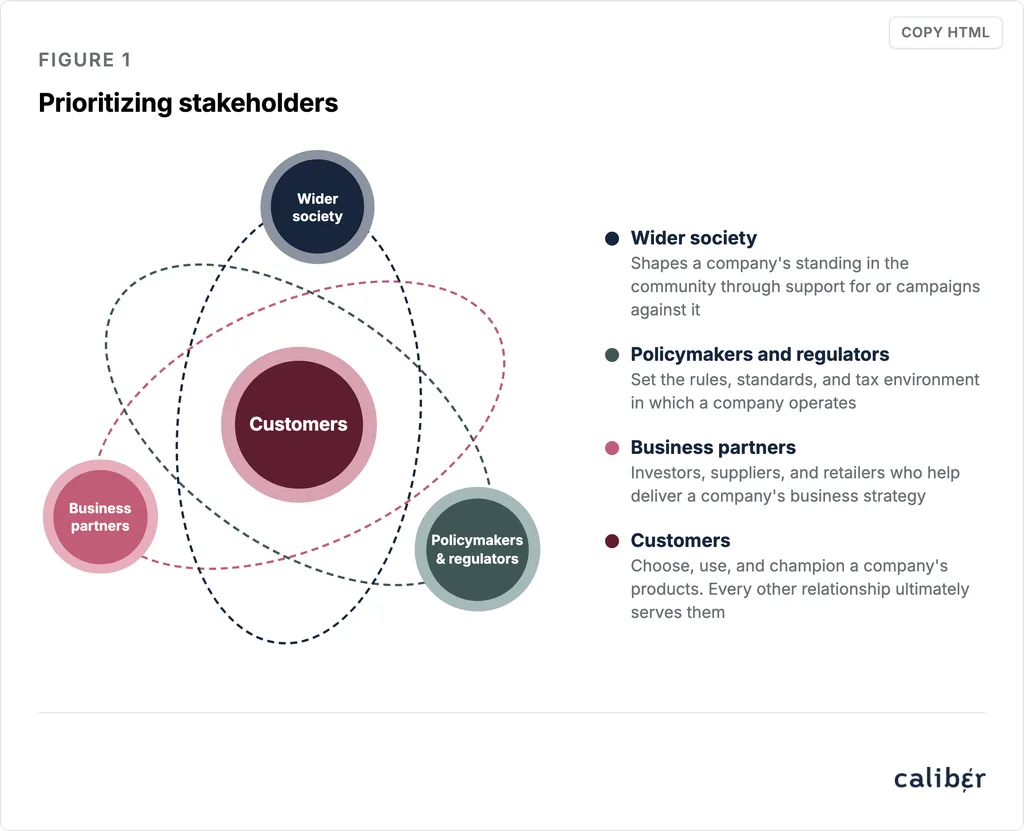
That split matters because different stakeholders judge FMCG companies on different grounds. A shopper, an investor, and a policymaker don’t assess a company the same way. Business decision-makers and key opinion leaders, such as journalists and NGOs, tend to be more skeptical and less moved by consumer marketing.
How the reputation of the FMCG industry moved in 2026
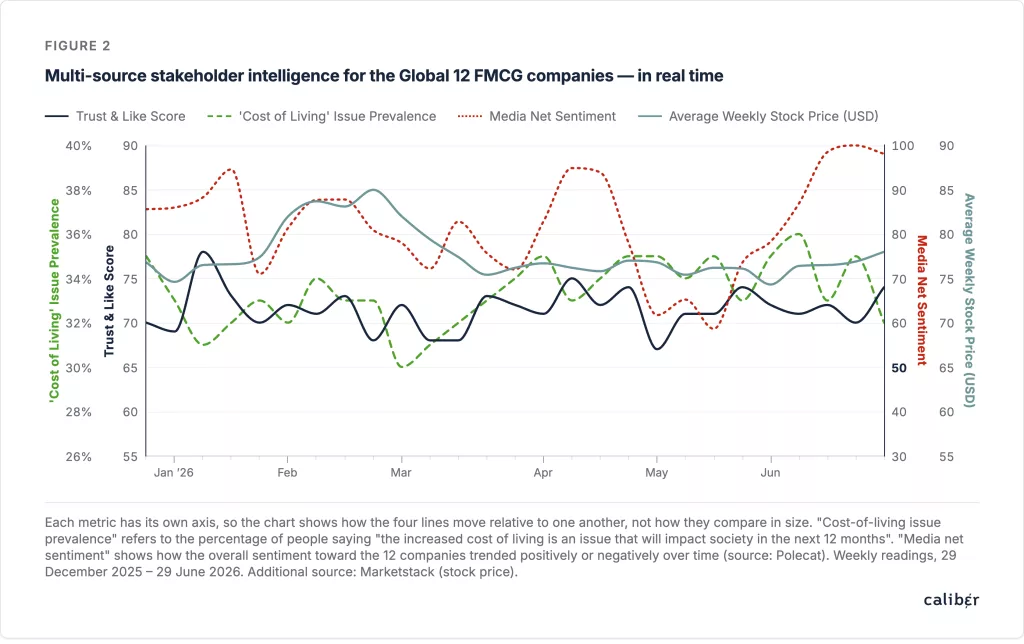
The FMCG industry’s reputation fell twice in the first half of 2026 and recovered both times. Caliber measures this with the Trust & Like Score, its chief measure of corporate reputation. Respondents rate companies on a 1 to 7 scale, which Caliber rescales to 0 to 100. Scores fall into five tiers: Very High (80 to 100), High (70 to 79), Average (60 to 69), Low (40 to 59), and Very Low (0 to 39). You can read more in Caliber’s guide to the Trust & Like Score.
Caliber tracks the score weekly, which shows when perceptions shift, rather than weeks or months later. The global TLS for the Global 12 rose sharply in mid-January 2026, as inflation eased and several FMCG companies announced price cuts. It reversed over the following fortnight.
The infant formula recall
The January drop lines up with a growing infant formula crisis. Nestlé, Danone, and Lactalis recalled batches worldwide over contamination with the toxin cereulide, according to Bloomberg reporting published by Swissinfo. Nestlé pulled products in more than 60 countries. A smaller TLS dip followed in late February, as EU regulators issued formal contamination guidance.
The May drop: cost of living and the ultra-processed food lawsuit
The global TLS fell again in May and reached its lowest point of the half-year. Two developments coincide with the drop. The rising cost of living, worsened by the Middle East conflict, pushed up energy, fertilizer, and freight costs and squeezed prices on everyday goods. A $1 billion US lawsuit, filed at the end of April, also accused major food companies of engineering addictive ultra-processed foods. Eight of the Global 12 were among the defendants.
Media sentiment and share price
Media sentiment and stakeholder trust moved together only loosely. In February, the TLS shifted first and media sentiment followed. In May, the order reversed: coverage turned negative just before the TLS fell, as headlines focused on manufacturers raising prices. Share prices behaved differently again, holding until March before dipping, after the TLS had already started falling in January.
Is the FMCG industry more trusted than other sectors?
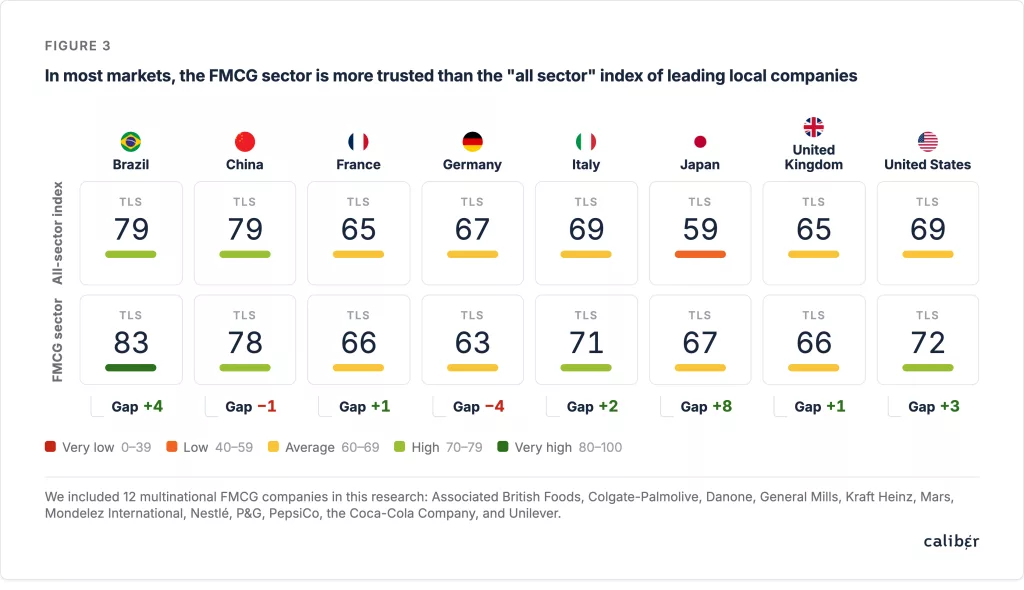
Yes, in most markets. Caliber compares the FMCG sector’s TLS with an “all sector” index of leading local companies in each market. The FMCG sector scores higher in six of the eight markets, with the biggest lead in Japan.
The FMCG industry market by market
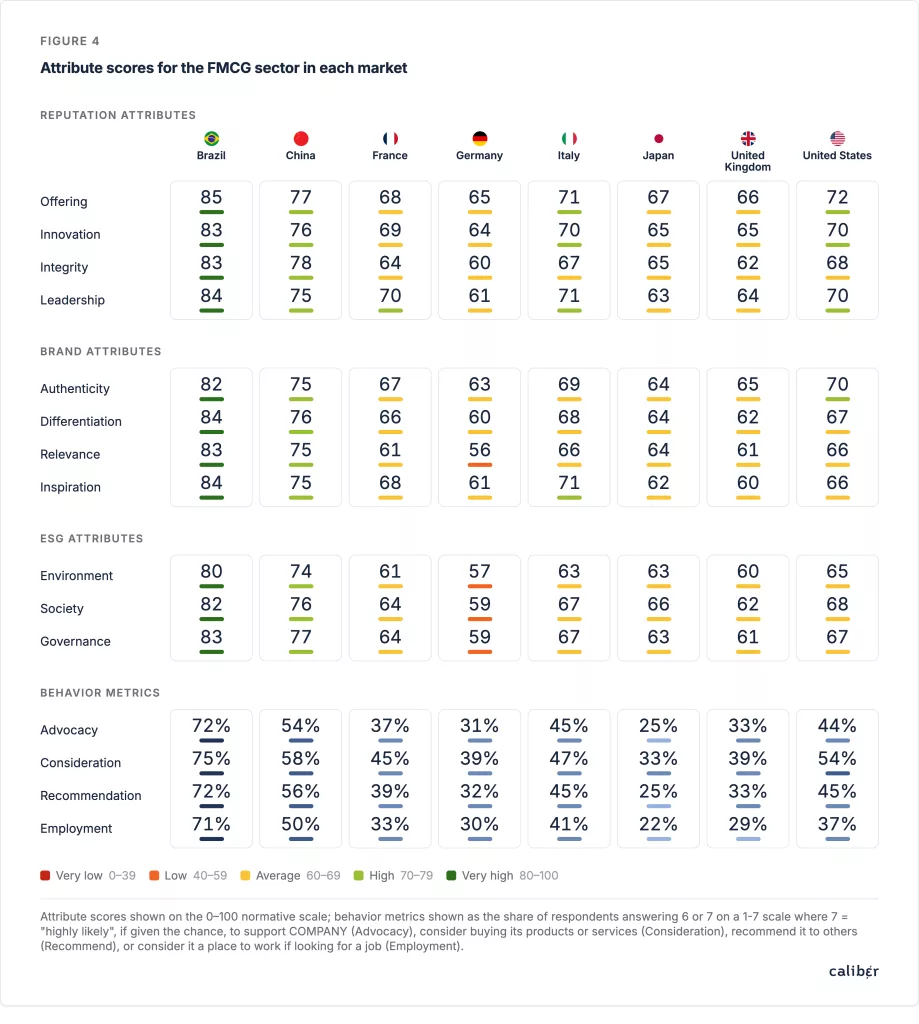
Brazil is the only market where the FMCG sector reaches the Very High tier, with a TLS of 83. Germany is the outlier at the other end. Its FMCG TLS of 63 is four points below the local index, which appears to be driven by weak perceptions of the sector’s ESG impact and its Relevance.
Why the FMCG industry struggles on Relevance in the West
Caliber tracks perceptions of companies across 11 brand, reputation, and ESG attributes. In most Western markets, the FMCG sector scores low on Relevance, meaning stakeholders find FMCG companies less relatable. The gap is clearest in France, Germany, and the UK. Possible explanations include “eat local” trends, health and wellness culture, or a weaker link between product brands and the companies behind them.
China and Brazil are the only markets where Relevance scores are high. Each market also has its own strengths. In China, Integrity is the FMCG sector’s highest-scoring attribute. In France, the sector scores relatively well on Innovation, which may reflect the influence of Danone and its focus on probiotics and plant-based products.
What drives trust in the FMCG industry?
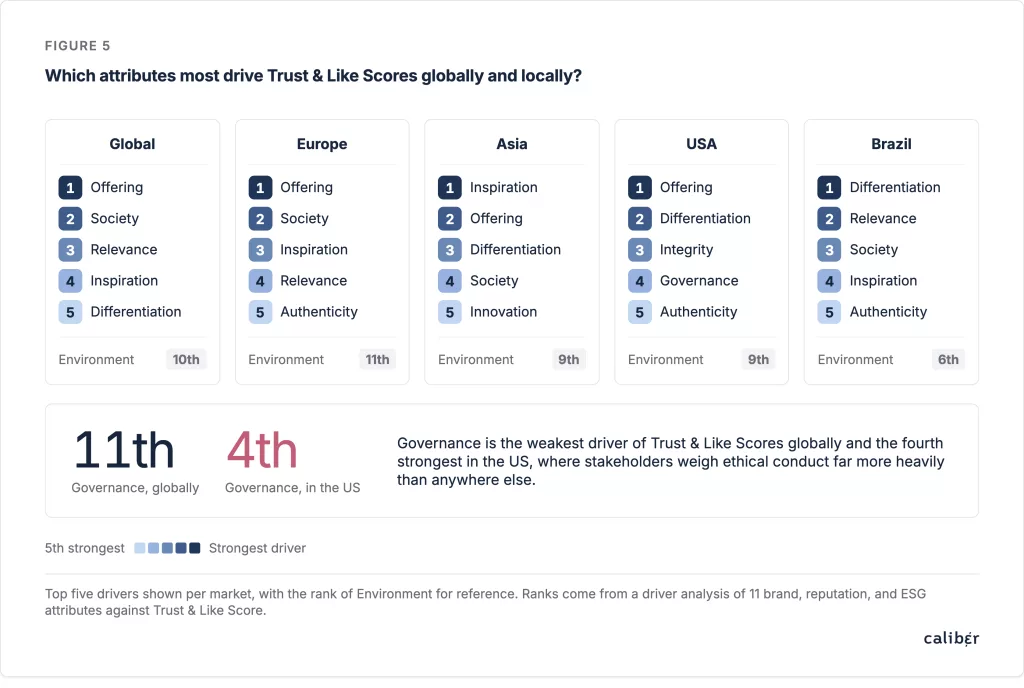
Offering is the strongest driver of trust in FMCG companies worldwide. Caliber defines Offering as the perception that a company has “compelling products or services.” Society, the perception that a company has “a positive impact on people,” is a close second globally and in Europe. Relevance ranks third globally.
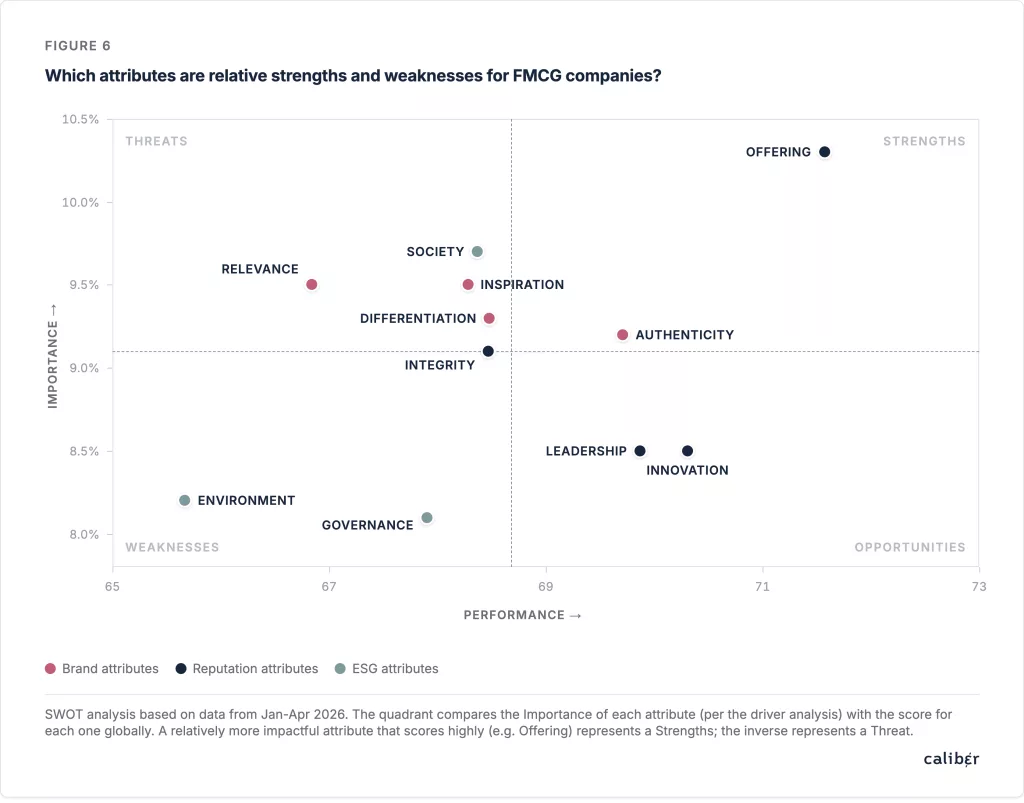
Caliber’s driver analysis measures how much each of the 11 attributes moves a company’s TLS. FMCG companies currently deliver more on product expectations than on societal ones, judging by their actual scores. The top driver and the weaker performance on Society point to where reputation gains are most available.
Why the US and Brazil break the pattern
The US and Brazil break the global pattern in opposite directions. Brazil is brand-led, with Differentiation and Relevance as its top two drivers. In the US, stakeholders weigh Integrity and Governance far more heavily than anywhere else. Governance is the weakest of the 11 drivers globally, but it ranks fourth in the US.
Differentiation matters far more outside Europe. It ranks in the top three in Asia, the US, and Brazil, but only eighth in Europe. One possible reading is greater price sensitivity outside Europe, where a brand has to stand out to justify its cost.
Environment and Governance: weak drivers, real risk
Environment and Governance are among the weakest drivers of trust in the FMCG industry. Environment ranks 10th globally and 11th in Europe. Environment scores are also comparatively weak in most markets. A company’s perceived impact on the planet may not be a stakeholder priority today, but it stays a background risk.
Caliber combines importance and performance in a quadrant. Attributes with high importance and low performance are threats to fix. Attributes with high importance and high performance are strengths to protect.
The most trusted companies in the FMCG industry in 2026
Colgate-Palmolive, Nestlé, and General Mills share the top Trust & Like Score among the Global 12, with a TLS of 74 each, in the High tier. Unilever and Mondelez International score lowest, with 68 each, in the Average tier.
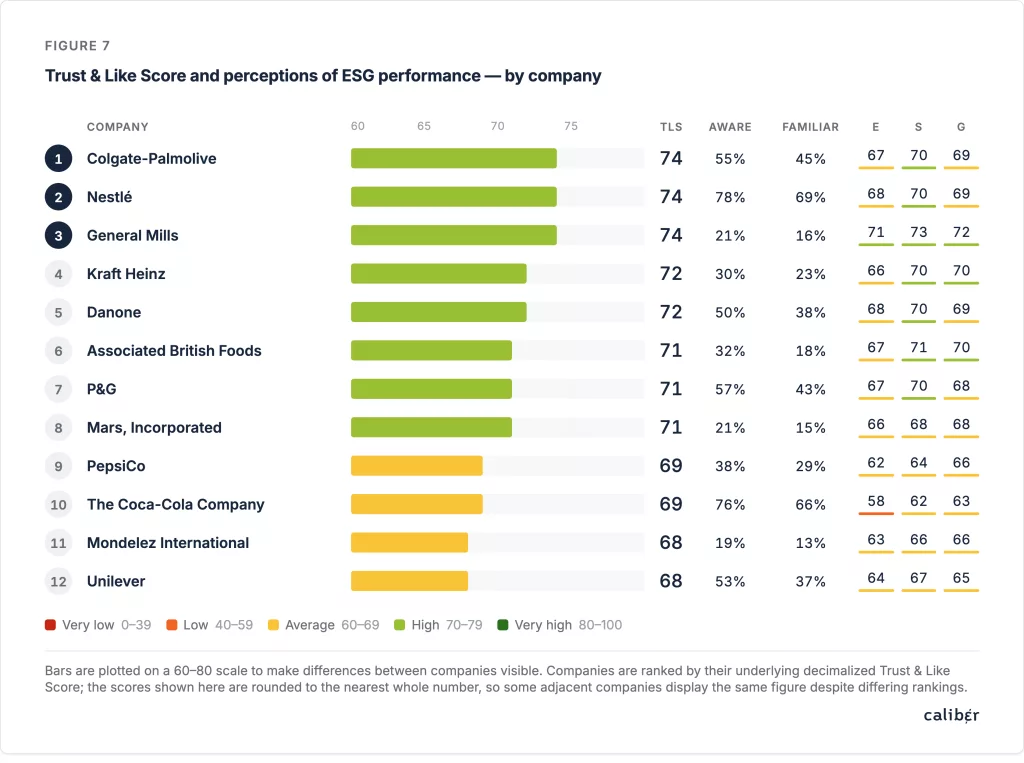
General Mills, Mondelez, Mars, Kraft Heinz, and Associated British Foods all have notably lower Awareness and Familiarity. They’re houses of brands, and their products are far better known than the companies themselves. Caliber’s research on familiarity explains why that gap matters for reputation.
Why Nestlé recovered so fast
Nestlé is the best-known company in the study, with 78% Awareness and 69% Familiarity. Its long history and much-loved products explain part of that, and a legacy of recalls and controversies likely adds to it. That familiarity also seems to give stakeholders an emotional bond with the company. Nestlé’s global TLS is more than three points higher than the average of its attribute scores.
That goodwill may explain why Nestlé recovered so quickly from the infant formula recall and now shares the top spot. The Coca-Cola Company has similar Awareness and Familiarity and its own emotional halo, but a lower TLS of 69. Its Environment score of 58 is the only Low-tier ESG score among the Global 12. A single-product identity gives it less insulation than Nestlé’s portfolio of brands, from Nescafé to KitKat.
Do FMCG brands build trust in the parent company?
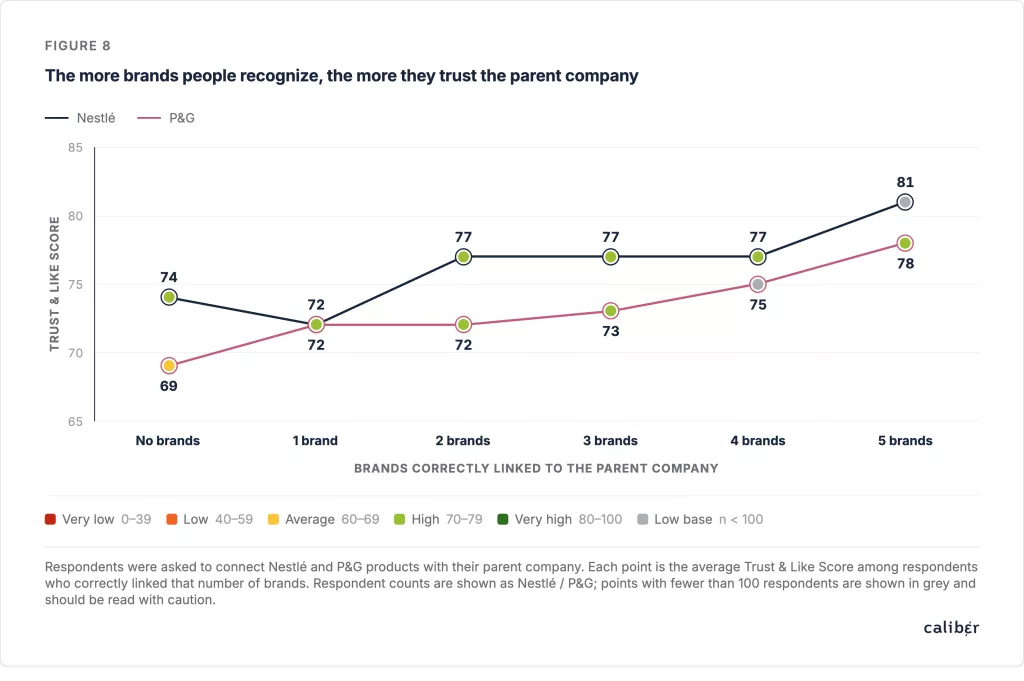
Yes. According to Caliber’s 2026 FMCG report, the more product brands people correctly link to Nestlé or P&G, the more they trust the parent company. Caliber asked respondents to connect Nestlé and P&G products with their parent company, then compared the average TLS by the number of brands linked.
The more brands people recognize, the more they trust the parent
Respondents who couldn’t link any P&G brand gave P&G a TLS of 69. Among those who linked all five, the score rose to 78. Nestlé shows a similar pattern, from 74 with no brands linked to 77 with two to four brands linked. Nestlé’s five-brand score of 81 rests on a small sample of fewer than 100 respondents.
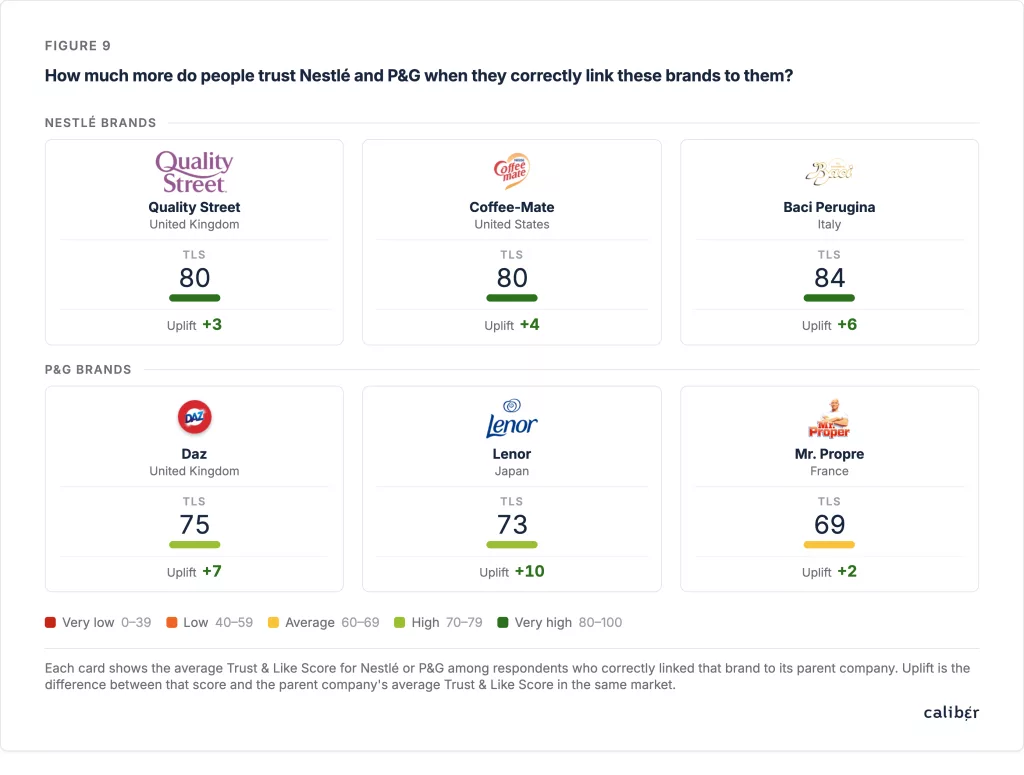
Single brands can move trust a long way. In Japan, P&G has a TLS of 63. Among people who correctly identify Lenor as a P&G brand, its TLS is 73, a 10-point lift.
Does brand damage travel up?
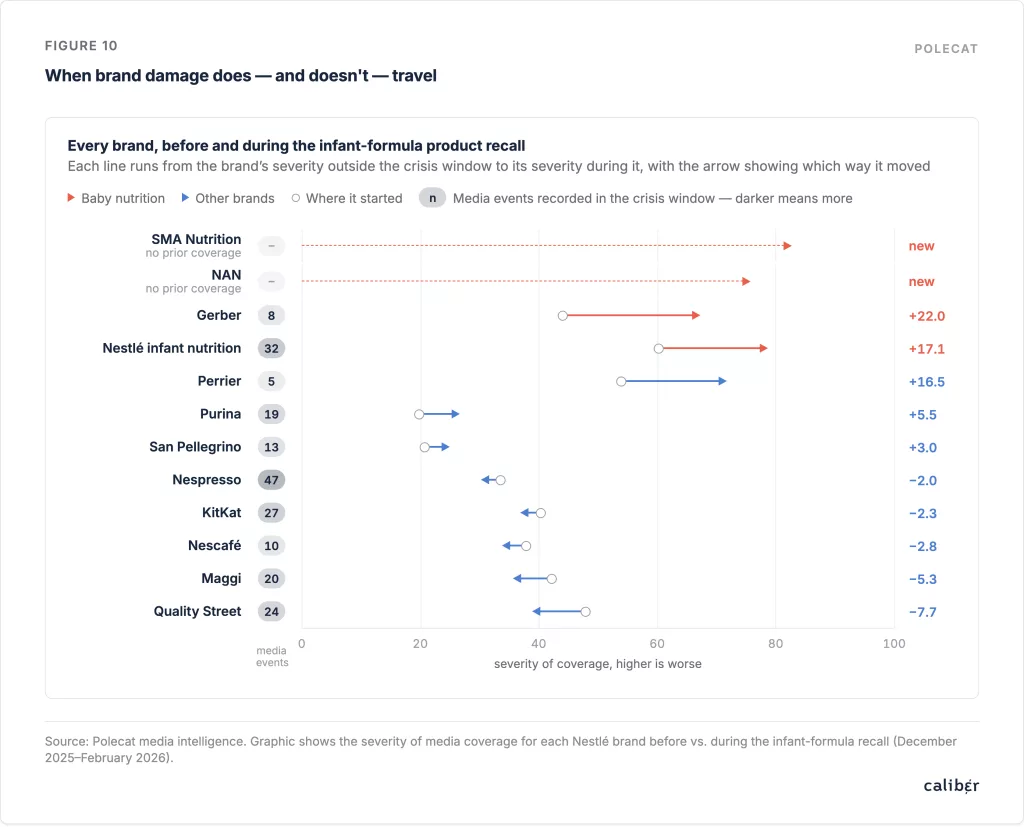
Brand-level damage didn’t travel up to Nestlé. Caliber’s media-intelligence partner Polecat tracked coverage of 12 Nestlé brands before and during the infant formula recall. Negative coverage rose 22 points for Gerber and 17 points for Nestlé’s own infant nutrition line on Polecat’s severity scale. NAN and SMA Nutrition appeared in coverage for the first time.
Most of Nestlé’s other brands held steady or improved, including KitKat, Nespresso, Nescafé, Maggi, and Quality Street. Perrier was the exception, worsening by 16.5 points over its own controversy about a French water treatment plant. Nestlé’s corporate TLS dipped early in the year and has since recovered. Houses of brands appear better shielded from crises than companies whose name is on the product.
Get the full FMCG report. See all 15 charts, market-by-market scorecards, and the complete risk analysis in In Goods We Trust: Risk and Reputation in FMCG. Read the report
How AI search is shaping trust in the FMCG industry
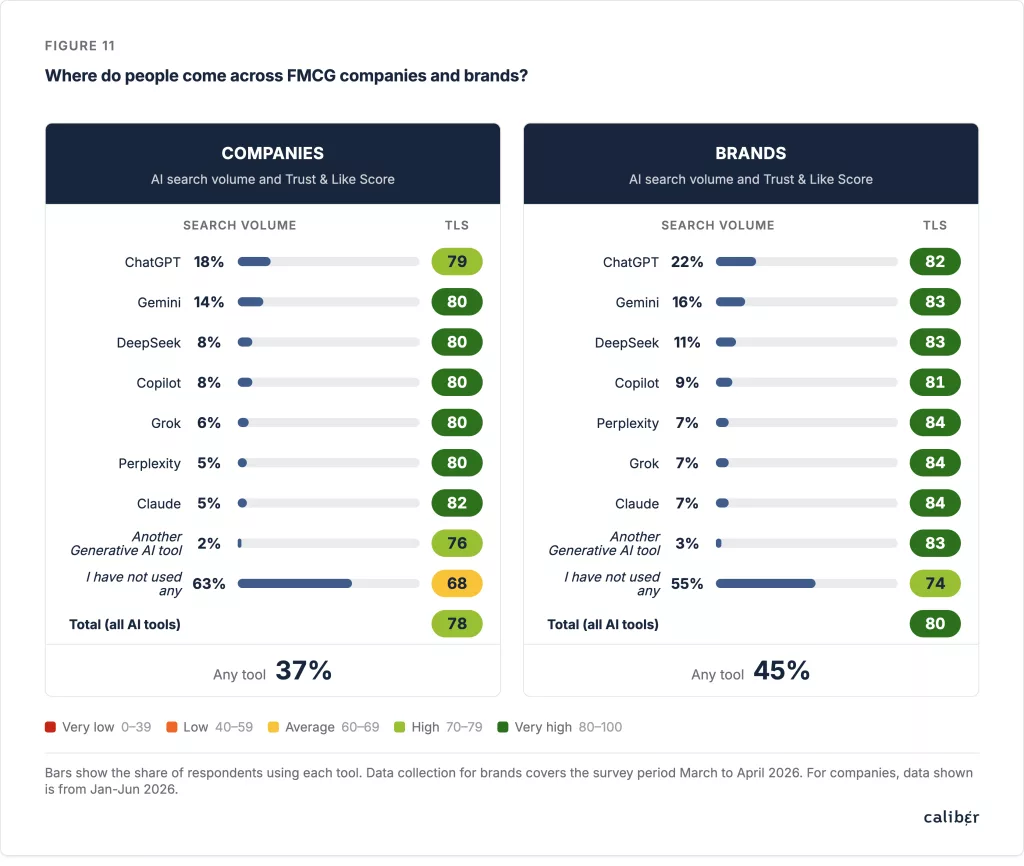
People who use AI tools to research the FMCG industry trust it more than people who don’t. According to Caliber’s 2026 FMCG report, AI users give FMCG companies an average TLS of 78, compared with 68 among non-users. For product brands, the gap is six points: 80 among AI users and 74 among non-users.
More people use AI to research FMCG brands than the companies behind them: 45% vs 37%. That suggests shoppers use tools like ChatGPT and Gemini to compare products before they buy. ChatGPT is the most used tool for both, at 22% for brands and 18% for companies, followed by Gemini. AI users are among the sector’s most trusting stakeholders. That makes what AI models say about FMCG companies worth tracking.
The biggest reputational risks facing the FMCG industry
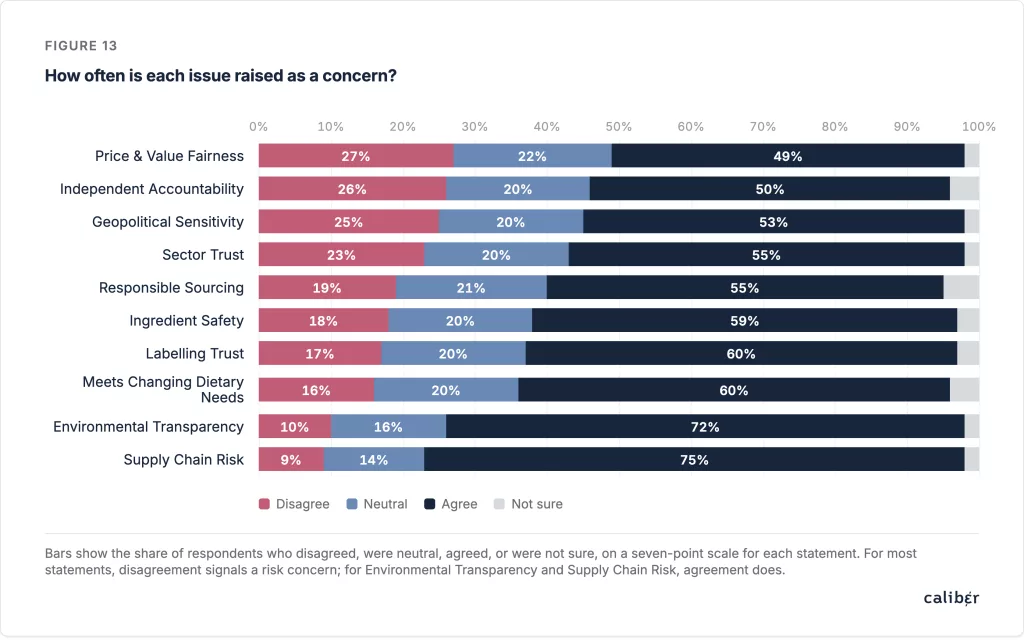
Responsible Sourcing and Ingredient Safety are the most damaging reputational risks in the FMCG industry, and both are within a company’s control. Caliber tested 10 risks by asking respondents how far they agree with one statement per risk. It then compared the TLS given by people whose answer signals a concern with the TLS given by everyone else. Caliber calls the gap the trust penalty.
The trust penalty in the FMCG industry
People who doubt that FMCG companies source ingredients and materials responsibly give the sector an average TLS of 53, in the Low tier. People who don’t share that doubt give it 78. That 25-point gap is the largest trust penalty of any risk.
| Reputational risk | Trust penalty (TLS points) | Raised as a concern |
|---|---|---|
| Responsible Sourcing | −25 | 19% |
| Ingredient Safety | −23 | 18% |
| Meets Changing Dietary Needs | −22 | 16% |
| Independent Accountability | −22 | 26% |
| Sector Trust | −22 | 23% |
| Labelling Trust | −21 | 17% |
| Geopolitical Sensitivity | −20 | 25% |
| Price & Value Fairness | −19 | 27% |
| Supply Chain Risk | +7 | n/a |
| Environmental Transparency | +15 | n/a |
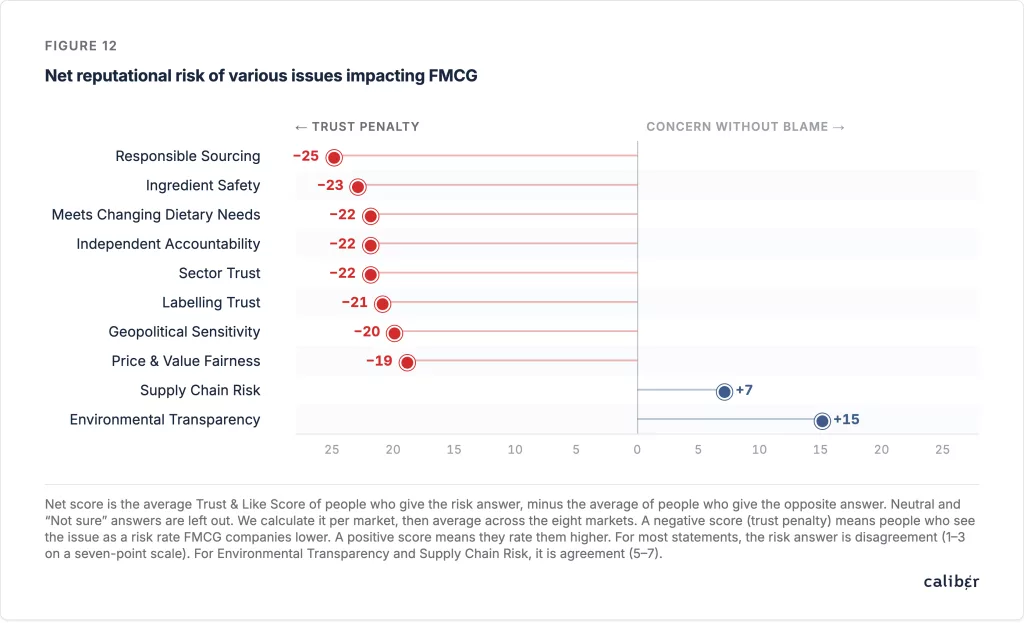
Two risks work differently. Environmental Transparency and Supply Chain Risk measure how much people care about an issue, not how they judge companies’ handling of it. People who share those concerns rate FMCG companies higher. They care about the issue but don’t blame the sector for it.
Three risk profiles
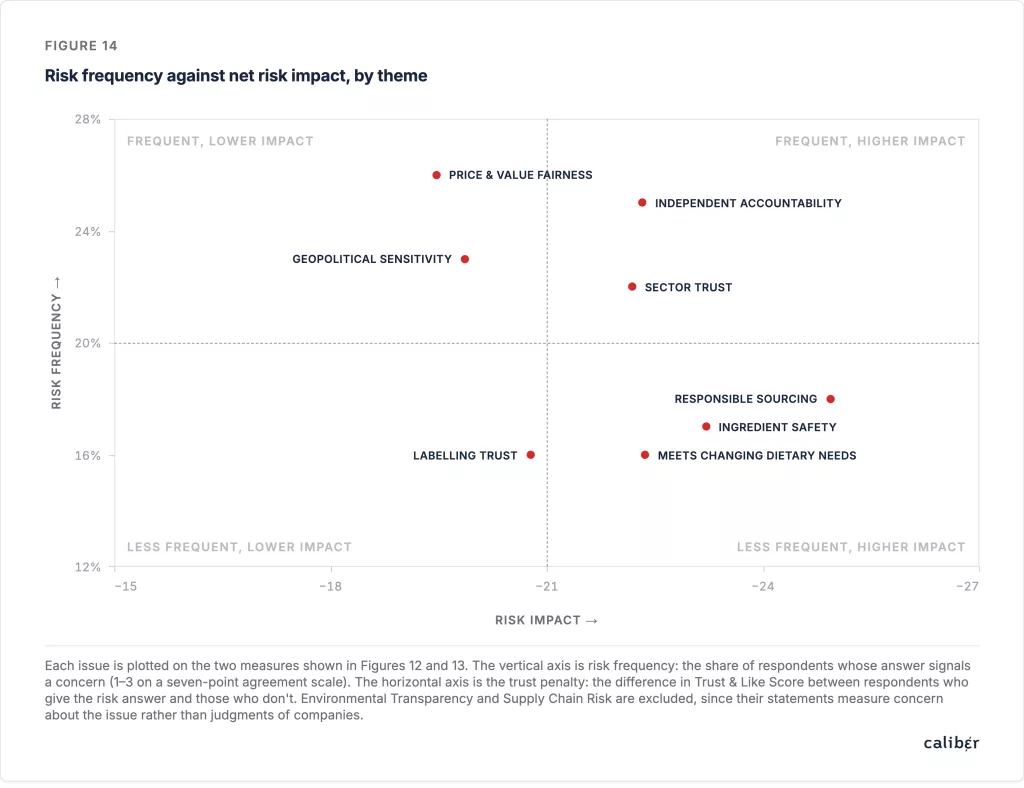
Every risk where disagreement signals concern carries a trust penalty of at least 19 points. Plotting how often each risk is raised against how much trust it costs gives three profiles:
- Frequent and damaging: Independent Accountability and Sector Trust are raised often and carry penalties of 22 points.
- Frequent and slightly less damaging: Price & Value Fairness is the most common concern, at 27%, closely followed by Independent Accountability and Geopolitical Sensitivity.
- Less frequent and most damaging: Responsible Sourcing, Ingredient Safety, and Meets Changing Dietary Needs are raised less often but do the most harm when they are.
Key opinion leaders see more risk
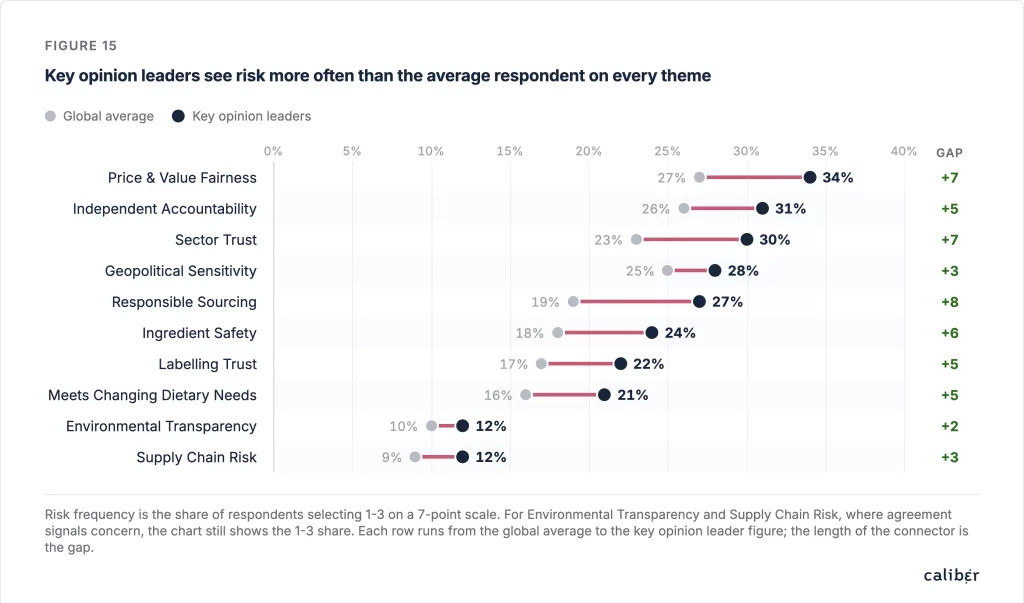
Key opinion leaders, such as journalists, influencers, and NGOs, see risk more often than the average stakeholder on all 10 themes. The widest gaps are on Responsible Sourcing (27% vs 19%), Price & Value Fairness (34% vs 27%), and Sector Trust (30% vs 23%). Their views matter because they shape how everyone else sees the sector.
What this means for FMCG industry leaders
The FMCG industry ends the first half of 2026 tested but resilient. It’s still more trusted than most sectors in the majority of markets, and its strongest companies recovered quickly from crisis. Caliber’s data points to three lessons for chief communications officers and marketing leaders.
- The stakeholder map is fragmented. Integrity and Governance matter more in the US, Brazil is brand-led, and ESG scores lag in Europe. A single global reputation strategy, applied uniformly, is likely to underperform.
- Trust runs mainly from product to company. Offering is the strongest driver of trust, and recognizing more of a company’s brands lifts trust in the parent. Brand-level crises tend to stay with the brand.
- The biggest risks are the ones you control. Responsible Sourcing and Ingredient Safety carry the heaviest trust penalties. That makes them the risks a company is best placed to manage.
Caliber tracked 12 FMCG companies through six turbulent months. Stakeholder 360 gives you the same always-on view of how stakeholders see your company, market by market and audience by audience. See how Caliber works with companies in the FMCG industry, or book a demo to see your own data.
Frequently asked questions about the FMCG industry
What is FMCG?
FMCG stands for fast moving consumer goods. These are everyday products that sell quickly, at low cost, and in high volume, such as packaged food, drinks, toiletries, cosmetics, and household cleaning products. Because people buy them often, FMCG brands are some of the most familiar in the world.
Which FMCG companies are the most trusted in 2026?
According to Caliber’s 2026 FMCG report, Colgate-Palmolive, Nestlé, and General Mills share the highest Trust & Like Score among 12 global FMCG companies, with a TLS of 74 each. Unilever and Mondelez International score lowest, at 68 each. The scores come from stakeholder surveys in eight markets between January and April 2026.
Is the FMCG industry trusted more than other sectors?
In most markets, yes. Caliber’s 2026 data shows the FMCG sector scoring above the “all sector” index of leading local companies in six of eight markets. The lead is largest in Japan (+8) and Brazil (+4). Germany (−4) and China (−1) are the exceptions.
What are the biggest reputational risks for FMCG companies?
Responsible Sourcing and Ingredient Safety carry the heaviest trust penalties, at 25 and 23 points. People who doubt FMCG companies source responsibly give the sector a TLS of 53, compared with 78 among those who don’t. Price & Value Fairness is the concern raised most often, by 27% of respondents.
Does a product brand crisis damage the parent FMCG company?
Caliber’s 2026 data suggests it usually doesn’t last. During the 2026 infant formula recall, negative media coverage rose sharply for Nestlé’s baby nutrition brands but not for most of its other brands. Nestlé’s corporate Trust & Like Score dipped early in the year, then recovered to share the top spot among 12 FMCG companies.